United Water Restoration Group of Dayton, OH


Fire Damage in Dayton: What Insurance Will (and Won’t) Cover
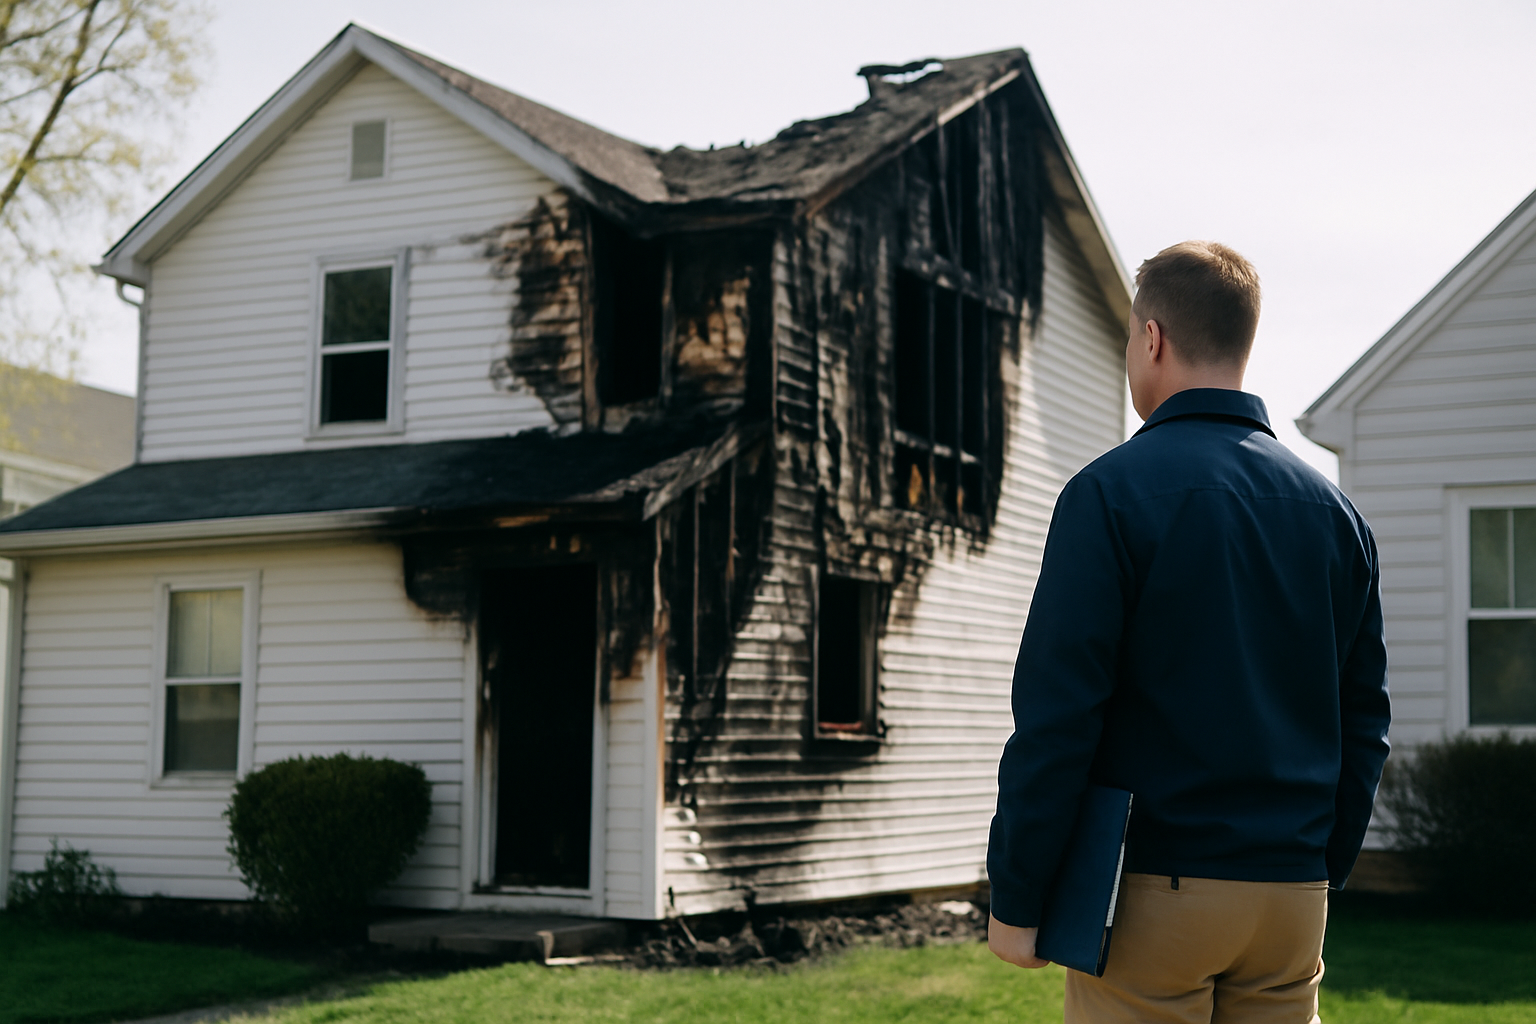
A kitchen fire is out in minutes, but the aftermath lasts for weeks. Soot coats the walls and water pools on the floor. For a Dayton homeowner, the next question is money. What will insurance actually pay for, and what falls on you?
Key Takeaways
- ›Most standard homeowners policies cover fire damage to the home, belongings, and living costs.
- ›Smoke and firefighting water damage are usually part of a covered fire claim.
- ›Arson by the owner and long-vacant homes are common exclusions.
- ›Fast documentation and prompt filing lead to smoother claims.
What a Standard Policy Usually Covers
A typical homeowners policy treats fire as a covered peril. It pays to repair or rebuild the structure up to your limits. It also covers personal belongings lost to the flames. If you cannot live at home, it helps with added living costs.
The Insurance Information Institute outlines what a standard policy covers, including the dwelling, personal property, and additional living expenses.
What Fire Insurance Often Will Not Cover
Coverage has limits worth knowing before disaster strikes. A fire set on purpose by the owner is never covered. A home left vacant for weeks may fall outside the policy. Some belongings, like cash or certain valuables, carry low caps.
Smoke and Water Damage After the Fire
Fire rarely acts alone. Smoke pushes into walls, ducts, and fabric far from the flames. Firefighting water soaks floors and drywall. Both are typically covered when they result from the fire itself.
Filing a Fire Claim in Dayton
Start with safety, then move quickly on the claim. Contact your insurer as soon as the scene is safe. Ask about emergency funds and temporary housing. Do not throw anything out until it is documented.
The Insurance Information Institute’s guide to settling claims after a disaster recommends prompt filing and detailed records.
Documenting Your Losses
The claim is only as strong as your records. Photograph every damaged room before cleanup begins. List lost items with a rough age and value. Keep receipts for lodging, meals, and supplies.
Restoring the Home After a Fire
Once the claim is moving, restoration can begin. Soot and smoke need specialized cleaning, not a household sponge. Water must be extracted and the structure dried.
A fire damage restoration crew in Dayton can handle soot, odor, and water together. United Water Restoration coordinates the cleanup so your claim and repairs stay aligned.
Understanding Your Deductible
Every fire claim starts with your deductible. That is the amount you pay before coverage kicks in. A higher deductible lowers your premium but raises out-of-pocket costs. Know the number before you need it.
Replacement Cost Versus Actual Cash Value
How your policy values items matters after a fire. Replacement cost pays to buy new equivalents. Actual cash value subtracts for age and wear. Check which one your policy uses for belongings.
Additional Living Expenses Explained
When a fire makes a home unlivable, this coverage helps. It can pay for a hotel, meals, and other added costs. Keep every receipt during that period. The coverage has limits, so track spending carefully.
Working With the Adjuster
An adjuster inspects the damage and estimates the loss. Walk the property with them and point out everything. Share your inventory and photos. A thorough walkthrough supports a fair settlement.
Why Soot Cleanup Is Specialized
Soot is acidic and spreads fast into porous surfaces. Wiping it wrong can smear and set the stain. Professionals use the right solvents and airflow control. Proper cleaning protects what the fire did not destroy.
Protecting the Property After a Fire
An open, damaged home invites more loss. Board up windows and tarp the roof to keep weather out. Secure the site against theft. Most policies expect you to prevent further damage.
The Timeline of a Fire Claim
Fire claims move in stages, not overnight. First comes the report and emergency funds. Then the inspection and estimate. Finally, approved repairs and reimbursement follow. Patience and records keep it on track.
Reviewing Coverage Before Trouble
The best time to read a policy is before a fire. Check your limits, exclusions, and deductible each year. Ask your agent about any gaps. A short review now prevents an unwelcome surprise later.
Renters and Fire Coverage
A landlord’s policy covers the building, not your belongings. Renters insurance fills that gap for tenants. It also pays for a place to stay after a fire. Tenants should confirm the coverage before they ever need it.
Keeping an Up-to-Date Home Inventory
A current inventory speeds any future claim. Photograph each room and note major purchases. Store the list in the cloud, not just at home. After a fire, that record saves hours of memory work.
Common Reasons Claims Get Delayed
Missing documents slow a claim more than anything. Vague loss lists invite extra questions from the insurer. Throwing out debris too early erases proof. Careful records keep the process from stalling.
The Emotional Side of a Fire Loss
A fire takes more than walls and furniture. Familiar spaces and keepsakes are hard to lose. Give yourself room to process it. A steady plan for the claim brings back a sense of control.
Frequently Asked Questions
After a Dayton Fire, Know Your Next Move
A house fire upends everything, and the insurance maze makes it harder. You do not have to sort the cleanup alone. Reach the United Water Restoration team through our contact page for a clear plan. We keep your claim and your home moving forward.
